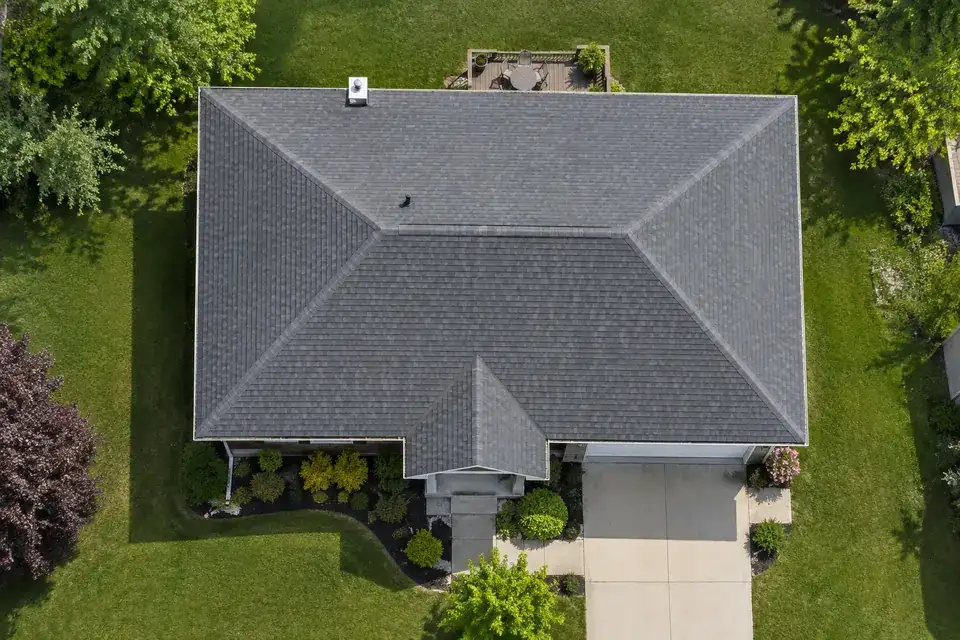
Start with the right area
Use the ground-floor footprint requested by this calculator. A two-story home’s total living area is not its footprint. Pitch, roof shape and waste are separate inputs; do not add them twice.
Home › Roof
Roof replacementEstimate a new roof from footprint, pitch, material, tear-off and regional assumptions. See itemized costs, then compare an illustrative insurance payout for covered damage. A house floor area is not the same as roof area.
Reviewed 25 October 2026 · Written by Mantu Kumar
See the illustrated project guide
2026 planning ranges
Diagram, part by part
The roof replacement drawing above has 9 numbered parts, from Tear-off, one layer to Steep pitch and two stories. Each card below frames one of them, and after you run the calculator it shows what that part adds to your estimate.
$2,100–$3,900
The crew strips the old shingles and underlayment down to the deck and hauls them away. One layer is the baseline; every extra layer adds labor, dump weight and often a second dumpster.
On the quote: Ask how many layers they found when they looked, and whether a second layer is already priced or would be a change order.
~$580–$970 at 10%
Decking is the plywood or OSB the shingles are nailed to. Nobody can see rot until the old roof is off, so good contracts price it per sheet rather than guessing a total.
On the quote: Get the per-sheet price in writing and a promise to photograph every replaced sheet.
Part of the materials
A rubberized membrane laid along the eaves and in valleys seals around nails where ice dams back water up. Many northern codes require it from the edge to 24 inches inside the warm wall.
What moves it: Climate, eave length and the number of valleys.
On the quote: Check that the quote names the eave width covered and includes the valleys.
Part of the materials
Synthetic underlayment covers the rest of the deck as a second water barrier under the shingles. It is light, tear-resistant and the default on almost every reroof today.
What moves it: Roof area and the product chosen.
On the quote: Make sure it covers the whole deck, not only the lower courses.
$400–$600 / sq
The shingles themselves, priced per square of 100 square feet. Architectural shingles cost more than three-tab but carry longer warranties and higher wind ratings.
On the quote: Compare squares with waste included; 10% to 15% is normal on a simple gable.
Permit $200–$550
The small parts that keep a roof watertight: the ridge vent, pipe boots, flashing details and the building permit. They are cheap individually and are where low bids cut corners.
On the quote: Look for new pipe boots and new drip edge, not ‘reuse existing’.
Part of a full replacement
Metal drip edge at the eaves and rakes guides water into the gutter and protects the deck edge. Step flashing at walls and new counter-flashing at chimneys are where most roof leaks start.
What moves it: Eave length, walls and chimneys on the roof.
On the quote: Ask for new drip edge and step flashing rather than reusing the old metal.
Adds labor and dump fees
Many older roofs have a second layer of shingles over the first. Each extra layer adds tear-off labor, weight in the dumpster and disposal fees, and most codes allow no more than two layers.
What moves it: How many layers are on the roof now.
On the quote: Ask how many layers were found and whether extra layers are priced or a change order.
Raises labor
Roofs steeper than about 8/12 need roof jacks and harnesses, and two- or three-story homes need more ladder and safety setup. Both slow the crew and raise labor per square.
What moves it: Roof pitch, stories and how easy it is to reach.
On the quote: Ask whether steep or high sections are priced at a higher rate.
A closer look at your project
The visible roof covering is only one part of a replacement project. Use the photograph to connect the roof you can see with the scope you need to price.

Three parts of the same picture, each tied to a line on a roof estimate. These close-ups are crops of the same AI-generated illustration.
Use the ground-floor footprint requested by this calculator. A two-story home’s total living area is not its footprint. Pitch, roof shape and waste are separate inputs; do not add them twice.
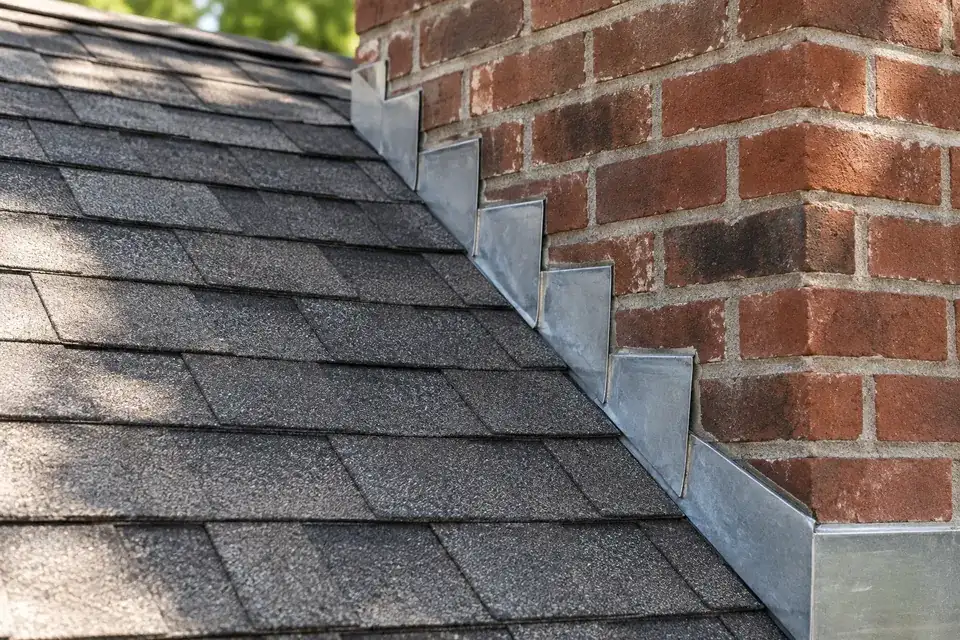
Ask whether the price includes removing old layers, underlayment, flashing, roof-edge work and disposal. The surface material alone does not describe a complete replacement.
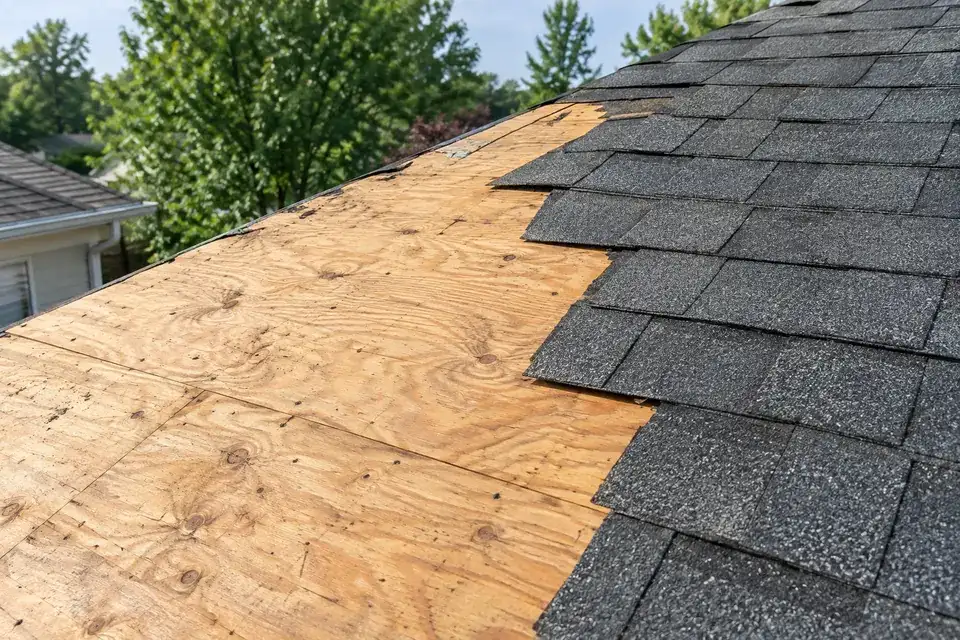
Damaged decking may only become clear when the covering is removed. Ask how extra sheets or repair areas would be measured, authorized and charged.
A roofing square is 100 square feet of roof surface. Every quote you receive is built on that unit, which is why two houses with identical floor plans can be quoted thousands apart.
The catch is that your roof is bigger than the house underneath it. A roof rising 6 inches for every 12 inches of run has 11.8% more surface than its footprint. At 12:12 it has 41% more. Add waste for cuts around valleys and dormers and a 1,800 sq ft footprint becomes roughly 23 squares of material. To work out your own number, use the roof area calculator.
| Pitch | Area multiplier | Walkable? |
|---|---|---|
| 2:12 — nearly flat | 1.014 | Yes |
| 4:12 — gentle | 1.054 | Yes |
| 6:12 — typical | 1.118 | With care |
| 8:12 — above average | 1.202 | Harnesses needed |
| 10:12 — steep | 1.302 | No |
| 12:12 — very steep | 1.414 | No |
Architectural asphalt, 6:12 pitch, one layer torn off, national average labor. Adjust for your own situation with the calculator above.
| Footprint | Squares | Typical range |
|---|---|---|
| 1,000 sq ft | 12.9 | $6,800 – $11,000 |
| 1,200 sq ft | 15.4 | $8,100 – $13,100 |
| 1,500 sq ft | 19.3 | $10,100 – $16,200 |
| 1,800 sq ft | 23.1 | $12,100 – $19,300 |
| 2,000 sq ft | 25.7 | $13,400 – $21,400 |
| 2,500 sq ft | 32.1 | $16,800 – $26,700 |
| 3,000 sq ft | 38.6 | $20,100 – $31,900 |
Every size worked through in detail — including how to measure your footprint from the ground, and why two contractors can quote different square counts on the same house.
Material choice does two things at once: it sets the price today, and it sets the depreciation schedule your insurer will use for the next few decades. A cheap roof is depreciated faster, so it is worth less at claim time as well as lasting less long.
| Material | Per square, installed | Expected life |
|---|---|---|
| 3-tab asphalt shingle | $300 – $500 | 20 yrs |
| Architectural asphalt | $400 – $600 | 28 yrs |
| Class 4 impact-resistant shingle | $550 – $900 | 32 yrs |
| TPO, low-slope membrane | $450 – $850 | 22 yrs |
| Modified bitumen, low-slope | $400 – $750 | 20 yrs |
| Corrugated metal | $500 – $900 | 45 yrs |
| Cedar shake | $700 – $1,300 | 30 yrs |
| Standing seam metal | $800 – $1,600 | 50 yrs |
| Clay or concrete tile | $1,000 – $2,000 | 55 yrs |
| Natural slate | $1,500 – $3,000 | 80+ yrs |
An actual-cash-value roof endorsement is not its own calculator and it is not a discount. It changes what a covered roof claim pays. Replacement cost pays to replace the roof, usually after the work is done and you claim the recoverable depreciation. An ACV roof endorsement pays the depreciated value. On an older roof that can be a small fraction of the job, and the deductible can erase it. Many forms switch an older roof to ACV at renewal. The declarations page is the only place that rule is real for your policy. This site does not treat one carrier’s age cutoff as if it applied to every policy.
Useful lives in the calculator are illustrations for the depreciation panel. The policy’s own schedule controls a claim. Run the depreciation calculator with the age on the declarations, and read the Texas hail guide if hail is the peril. A Class 4 shingle, a metal roof, or a tile roof is not a promised premium credit. Ask the carrier for a re-quote.
The material list now includes Class 4 impact-resistant shingles, TPO, and modified bitumen, beside the metal and tile that were already there. TPO and modified bitumen are low-slope membranes. Pick a low pitch for a flat or near-flat roof. A steep-pitch labor factor still applies if you select a steep pitch. The bands were widened because 2026 public guides do not agree.
This is where most homeowners get caught out, and it has almost nothing to do with the replacement cost itself.
First, the cause has to be covered. Hail, wind and falling trees generally are. Age, wear, poor maintenance and manufacturing defects generally are not. A roof that has simply reached the end of its life is not an insurable event, however expensive it is to replace.
Second, if the cause is covered, the amount depends on which kind of policy you hold:
| Replacement cost (RCV) | Actual cash value (ACV) | |
|---|---|---|
| First payment | Depreciated value, less deductible | Depreciated value, less deductible |
| After work is finished | Releases the withheld depreciation | Nothing further |
| Your share on an 18-year roof | Deductible only | Deductible plus the depreciation |
A buyback offer pays you a lump sum in exchange for excluding the roof from your policy going forward. Carriers use it on roofs they no longer want to insure. It is not an upgrade and it is not a settlement of a claim — after a buyback, roof damage is simply not covered. Read the endorsement before accepting one.
Labor is usually 50 to 60% of the bill. A crew is on your property for two to four days, working at height, carrying several tons of material up a ladder and several tons of old material back down. That is the bulk of what you are paying for.
The rest is spread across items that rarely appear in the headline number: underlayment, ice and water shield along the eaves, drip edge, ridge vent, flashing around every penetration, and disposal fees that have risen sharply. Tear-off alone runs $90 to $170 a square per layer, and HomeAdvisor puts total removal and disposal at $1,500 to $4,500.
Then there is the item nobody can quote accurately: the decking underneath. Its condition is unknown until the old roof comes off. Assume around 10% will need replacing and treat anything less as a good outcome.
This is an illustration from this page’s calculator, not a quote. Inputs: 1,800 sq ft footprint, 6:12 pitch, average waste (15%), one tear-off layer, 10% of the deck replaced, one story. Pitch multiplier is √(1 + 0.5²) = 1.118, so the roof surface is about 2,012 sq ft and the order quantity is 23.1 squares. The homepage’s $16,805 point sits inside the national range below.
| Surface after 6:12 pitch | 2,012 sq ft |
| Squares after 15% waste | 23.1 |
| Architectural shingles, national index 1.00 | $9,257 – $13,886 |
| Tear-off, one layer | $2,083 – $3,934 |
| Decking, 10% of the roof | $579 – $972 |
| Permit, before the regional index | $200 – $550 |
| Same house, South / Lower Midwest × 0.87 | $10,543 – $16,828 |
| Same house, Northeast metro × 1.26 | $15,270 – $24,371 |
| Same house, West Coast metro × 1.30 | $15,754 – $25,145 |
| National planning range | $12,119 – $19,342 |
There is no separate city price list. A city changes the labor index and the local permit, not the geometry. Climate changes a different line: ice-and-water shield in a cold climate, a wind or hail percentage deductible on the Plains (see the hail deductible calculator), and faster UV aging in a hot climate. Those are not baked into the three ranges above. Run the calculator with your index rather than trusting a single city average.
Most US homeowners replacing asphalt shingles pay between $9,000 and $23,000. Roof area drives the figure rather than house size, and area depends on pitch — a steep roof can be 30% larger than the footprint beneath it.
Only for sudden covered perils — hail, wind, fire, falling trees. Wear and age are excluded by nearly every policy. If the cause is covered, how much you receive then depends on whether you hold an RCV or ACV policy.
An offer to pay you a lump sum in exchange for excluding the roof from future coverage. It ends your roof cover rather than improving it.
Coverage often narrows with age. Many carriers move roofs past 15 or 20 years onto actual cash value automatically, and some decline to renew altogether. Check your declarations page rather than assuming the terms you signed up to still apply.
Repair when damage is localized and the roof still has years left. Replace when the roof is past roughly 75% of its expected life, when repairs are recurring, or when granules are shedding across the whole surface. Repeated repairs on an old roof rarely work out cheaper.
Three-tab asphalt around 20 years, architectural asphalt around 28, metal 45 to 50, tile 55, slate 80 or more. Ventilation matters as much as material — a poorly ventilated attic can take years off any roof.
Not for your own home in the ordinary case. Repairs on a rental property are generally deductible as an expense, while a full replacement is usually capitalized and depreciated. Energy efficiency credits can apply to certain roofing products. Worth confirming with a tax professional for your own situation.
In most US jurisdictions, yes, for a full replacement. Your contractor normally pulls it and includes the fee. Skipping it can cause problems at resale and can give an insurer grounds to question a later claim.
Sometimes. A reroof, or overlay, puts one new layer of asphalt shingles over one existing layer and skips the tear-off line, which at this calculator’s defaults is $2,229 to $4,210. Building codes based on the International Residential Code do not allow a new layer over two existing layers, over wet or deteriorated roofing, or over wood shakes, slate or tile. An overlay also hides the decking, adds weight and can shorten some shingle warranties. To approximate it here, set “Existing layers to remove” to None, or price both options side by side with the overlay vs tear-off calculator.
No. It prices a full replacement: area, tear-off, decking, materials and permit. A repair is priced per job: use the roof repair calculator for a patch, pipe boots, a valley or a tarp, and the roof damage guide for what to do first after storm or leak damage.
Primary public references anchor labor, price movement and insurance terminology. Calculator rates remain planning assumptions tested against published market ranges.
These organizations do not endorse ReplaceCost. Local contractor quotes, permits, product specifications and the written insurance policy control the real result. See the full methodology for the source hierarchy and update process.
Use these compact topics to move from a rough estimate to a quote-ready plan.
Common wording people use when comparing costs, estimates and next steps.
Each tool itemizes the work, shows a planning range, and explains how age, depreciation and your deductible can change the insurance check.
Planning summary: Start with the physical replacement estimator, then run the Claim gap tool with the replacement figure, item age, expected life and deductible from your declarations page. The result is a planning estimate — not a contractor quote or coverage decision.